Revenue, Costs, Profit, Assets, Liabilities and Equity Explained
What does it mean when a business reports rising revenue, falling profit or increasing liabilities? These words describe different parts of its financial story. Confusing them can lead to poor decisions, even when the figures themselves are correct.
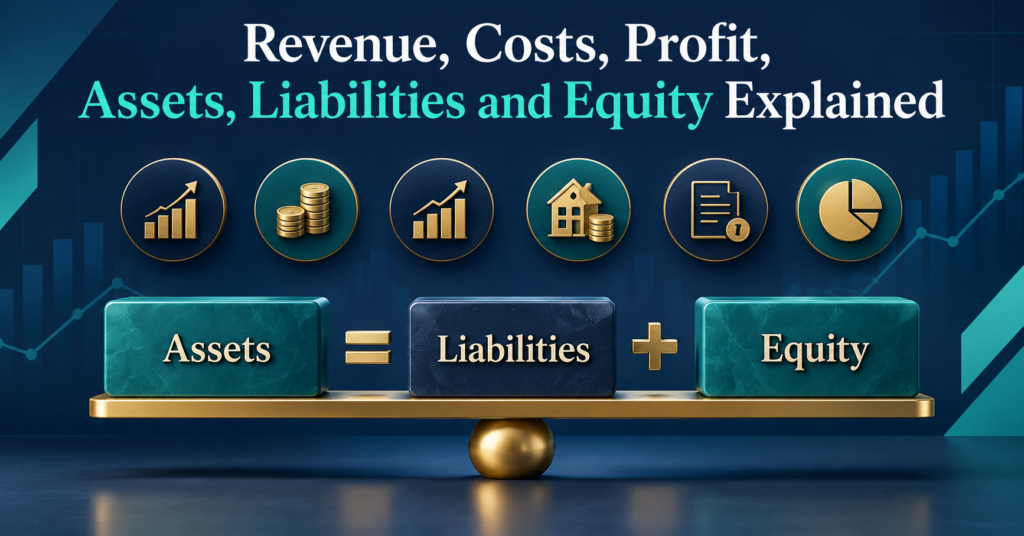
In simple terms, revenue is earned through ordinary business activities, costs measure resources acquired or used, expenses are costs recognised during a reporting period, and profit is what remains after relevant expenses have been deducted from income. Assets are controlled economic resources, liabilities are present obligations, and equity is the residual interest after liabilities are deducted from assets.
Understanding these business finance terms makes it easier to interpret reports, discuss performance and recognise why cash in the bank does not provide a complete picture of financial health.
Revenue: the value earned from ordinary activities
Revenue is the income generated by an organisation’s ordinary activities. A retailer earns revenue from selling goods, a consultancy earns it by providing professional services, and a subscription business earns it by giving customers access to its service.
Revenue is not necessarily the same as cash received. Suppose a consultancy completes a £12,000 project and gives the customer 30 days to pay. The consultancy may have earned £12,000 of revenue even though the cash has not yet reached its bank account.
The reverse can also happen. If a customer pays a deposit before a service is provided, receiving cash does not necessarily mean that the full amount has been earned. Under IFRS 15, revenue is recognised when or as the business satisfies its promise to transfer the relevant goods or services to the customer.[2]
Gross and net revenue should also be distinguished. If a retailer invoices customers £480,000 but accepts £8,000 of returns and grants £4,000 of agreed discounts, its net revenue is:
Net revenue = £480,000 − £8,000 − £4,000 = £468,000
The £468,000 represents the sales value retained after those deductions. It is still not profit because the business must account for the resources used to generate the sales.
Costs and expenses: related but not identical
A cost is the monetary value of a resource acquired or used for a business purpose. An expense is a cost recognised in calculating performance for a particular reporting period.
The distinction matters because paying for something does not always create an immediate expense of the same amount. Consider three £24,000 payments:
- Paying £24,000 for 12 months of insurance initially creates a prepayment asset. The cost is recognised as an expense over the period of cover.
- Buying £24,000 of inventory creates an asset while the goods remain available for sale. The relevant cost is normally recognised as an expense when the inventory is sold.
- Buying £24,000 of equipment creates a non-current asset. Its cost is generally allocated across its useful life through depreciation.
The cash payment is identical in each example, but the financial meaning is different.
Costs can also be classified according to how they relate to business activity. A direct cost can be traced to a particular product, service or project. An indirect cost supports several activities and cannot be traced as easily to one output.
For example, a consultancy spends 120 hours on a project and pays the consultant £40 per hour. It also purchases £200 of software access specifically for that work:
Direct labour cost = 120 × £40 = £4,800
Total direct project cost = £4,800 + £200 = £5,000
Office rent and general administration may be indirect costs because they support multiple projects. Managers may allocate a share of those costs to each project, but the allocation method is a management assumption that should be understood and applied consistently.
Profit: what remains after expenses
Profit is the amount by which recognised income exceeds recognised expenses during a period. A loss occurs when expenses exceed income.
Several profit measures may appear in financial reports:
- Gross profit is revenue minus the direct cost of the goods or services sold.
- Operating profit deducts operating expenses, such as administration and premises costs, from gross profit.
- Net profit incorporates further relevant items, which may include finance costs and tax depending on the reporting format.
Suppose a business reports net revenue of £468,000 and cost of sales of £280,000:
Gross profit = £468,000 − £280,000 = £188,000
If operating expenses are £130,000:
Operating profit = £188,000 − £130,000 = £58,000
The business has generated £468,000 of net revenue, but its operating profit is £58,000. Treating those figures as though they meant the same thing would seriously overstate performance.
Revenue growth does not guarantee profit growth either. If revenue rises by 10% while the relevant costs rise by 18%, profit may decline. Managers therefore need to examine both the income generated and the resources consumed.
Assets: resources controlled by the business
An asset is a present economic resource controlled by an organisation because of past events. The resource is a right with the potential to produce economic benefits.[1]
Common assets include:
- cash held in a bank account;
- trade receivables owed by customers;
- inventory held for sale;
- equipment and vehicles;
- property; and
- certain contractual or intellectual-property rights.
Assets are often divided into current and non-current categories. Current assets are generally expected to be realised, sold or consumed through the normal operating cycle or within the relevant short-term reporting period. Non-current assets usually support the organisation over a longer period.
Not everything valuable to a business automatically qualifies as an accounting asset. The organisation must control the relevant economic resource, and recognition in financial statements may require further criteria to be met. This is why everyday descriptions of what a business “owns” do not always match the items recognised in its accounts.
Liabilities: obligations the business must settle
A liability is a present obligation to transfer an economic resource as a result of past events.[1] It reflects a claim against the organisation’s resources.
Examples include:
- unpaid supplier invoices;
- bank and other borrowing;
- tax liabilities;
- wages already earned by staff but not yet paid; and
- obligations to provide goods or services for which a customer has paid in advance.
A liability is not automatically evidence that a business is failing. Borrowing may allow an organisation to purchase productive equipment or fund a carefully planned expansion. The important questions concern the purpose, amount, cost and timing of the obligation, together with the organisation’s capacity to settle it.
Consider a delivery company buying a van for £30,000. It pays £10,000 from its bank account and finances the remaining £20,000 with a loan. The transaction:
- increases vehicle assets by £30,000;
- reduces cash assets by £10,000; and
- creates a £20,000 loan liability.
The loan brings cash or purchasing power into the business, but it is not revenue. It creates an obligation to repay the lender.
Equity: the residual interest
Equity is the residual interest in an organisation’s assets after all its liabilities have been deducted.[1] The basic accounting equation expresses the relationship:
Assets = Liabilities + Equity
It can also be rearranged:
Equity = Assets − Liabilities
If a company controls assets of £340,000 and has liabilities of £155,000:
Equity = £340,000 − £155,000 = £185,000
The equation can be checked as follows:
£155,000 liabilities + £185,000 equity = £340,000 assets
Equity is not simply the cash available to the owners. The residual value may be represented by inventory, receivables, equipment and other assets. Equity can be affected by owner investment, distributions and accumulated results over time.
How the six business finance terms work together
The terms become most useful when they are interpreted as a connected system.
Imagine that Maple Print Ltd reports:
- revenue of £720,000;
- cost of sales of £390,000;
- operating expenses of £250,000;
- assets of £460,000; and
- liabilities of £275,000.
Its results are:
Gross profit = £720,000 − £390,000 = £330,000
Operating profit = £330,000 − £250,000 = £80,000
Equity = £460,000 − £275,000 = £185,000
Each result answers a different question. Gross profit shows what remains after the cost of sales. Operating profit shows performance after other operating expenses. Equity describes the residual financial position at the reporting date.
The £80,000 profit does not reveal how much cash Maple has. Some revenue may still be held in receivables, while cash may have been used to purchase inventory or equipment. Profit measures performance across a period; assets, liabilities and equity describe financial position at a point in time.
Common financial terminology mistakes
Calling every cash receipt revenue
A bank loan increases cash but also creates a liability. Owner investment increases cash and equity. Neither transaction is ordinary trading revenue.
Assuming revenue means profit
Revenue is recorded before the relevant expenses are deducted. A business can achieve strong sales and still make a loss if its costs are too high.
Treating every purchase as an immediate expense
Some purchases create assets that provide benefits over more than one reporting period. Their cost may be recognised as an expense later or gradually.
Treating equity as spare cash
Equity is a residual accounting interest, not a separate pot of money. A business can report substantial equity while holding relatively little cash.
Assuming every liability is harmful
Liabilities create obligations and risk, but some borrowing can support productive investment. The commercial effect depends on how the funds are used and whether the obligation remains manageable.
Why managers need accurate financial vocabulary
Clear terminology improves planning and decision-making. A request to “reduce costs” is incomplete until managers know which costs are involved, how they behave and what consequences a reduction could create. Cutting maintenance may improve short-term profit but undermine the reliability of an important asset. Taking a loan may increase available cash while also increasing liabilities and future finance costs.
Consistency matters as well. If a business changes what it includes within a category, an apparent trend may result from reclassification rather than a genuine improvement. Managers should therefore check definitions, accounting policies and supporting notes before drawing conclusions from headline figures.
Accurate vocabulary does not turn every manager into an accountant. It gives managers a shared language for asking better questions: What has been earned? Which resources have been consumed? What does the organisation control? What must it settle? What remains after those obligations?
Develop your understanding of business finance
Understanding financial terminology provides a foundation for budgeting, financial reporting, investment appraisal and organisational decision-making. Click College offers several flexible routes for learners who want to develop that knowledge further:
- The Professional Diploma in Finance is a focused 40-credit introduction to business finance and investment decision-making.
- The Higher International Certificate in Finance Management is a 120-credit Level 4 qualification combining finance with wider business and organisational knowledge.
- The Higher International Diploma in Finance Management incorporates Level 4 and extends the pathway to 240 credits in total.
- The International Graduate Diploma in Finance Management incorporates the Level 5 pathway and develops finance and strategic-management learning across 360 credits in total.
Compare the complete range of Finance Management courses and select the route that best matches your existing knowledge and professional goals.
Frequently asked questions
What is the difference between revenue and profit?
Revenue is earned through ordinary business activities before relevant expenses are deducted. Profit is the amount remaining after the applicable expenses have been recognised.
Is cash received always revenue?
No. Cash received from a loan creates a liability, while owner investment affects equity. A customer payment received in advance may also remain a liability until the promised goods or services are provided.
What is the difference between a cost and an expense?
A cost measures a resource acquired or used. An expense is a cost recognised in calculating performance for a particular period. A cost may initially be recorded as an asset before becoming an expense.
Is equipment an asset or an expense?
Equipment is normally recorded as an asset when it is expected to support the business over more than one period. Its cost is generally recognised as an expense gradually through depreciation, subject to the applicable accounting requirements.
What is the accounting equation?
The accounting equation is Assets = Liabilities + Equity. It shows that the resources controlled by an organisation are financed through obligations to others and the residual interest attributable to equity holders.
Can a profitable business have little cash?
Yes. Profit and cash are different. Revenue may not yet have been collected, cash may be invested in inventory or equipment, and the business may need to settle liabilities even though it reports a profit.
References
[2] IFRS Foundation, IFRS 15 Revenue from Contracts with Customers
Develop Your Finance and Management Skills
Want to develop your understanding of finance and business management? Explore Click College’s Finance Management courses and choose the flexible online qualification that best supports your next step.
Alternatively, view our Business Management courses and start studying online today.
Recent Posts
Level 4 Business Management Courses: 40 or 120 Credits
Level 4 Business Management Courses: 40 or 120 Credits Click College offers two Level 4 Business Management courses: a focused 40-credit Professional Diploma and a broader 120-credit Higher International Certificate. The Professional Diploma suits learners seeking a shorter introduction or targeted professional development. The Higher International Certificate suits those seeking a more comprehensive foundation in […]
What Are Management Accounts? How Internal Reports Support Better Decisions
What Are Management Accounts? How Internal Reports Support Better Decisions They usually combine financial information—such as sales, costs, profit and cash flow—with operational measures that explain the numbers. A useful management-accounting report does not simply state that profit fell or costs increased. It helps managers understand why, decide what to investigate and identify possible action. […]
Why a Profitable Business Can Still Have a Loss-Making Product or Department
Why a Profitable Business Can Still Have a Loss-Making Product or Department A business can make a healthy overall profit while one of its products, departments, locations or projects makes a loss. This is not a contradiction. Overall profit combines the results of many different activities. A profitable product line may generate enough contribution to […]